Reagan County, Texas Minerals: Who Owns What Before Anyone Talks Value
MINERAL RIGHTS & ROYALTIES
What could your mineral rights be worth?
Tell us a little about your interest. Get a free, no-obligation review from Selling My Mineral Rights.
If an offer letter for your Reagan County minerals is on the kitchen table, the number on it is the last thing worth studying. In most Permian counties you can work straight from a royalty check to a valuation. Here you usually cannot, because two older questions come first: whether the acreage under your tract is privately ownable at all, and what a century of West Texas deeds left you. Get those wrong and the valuation is arithmetic on the wrong asset.
Big Lake, 1923, and why title work here starts so early
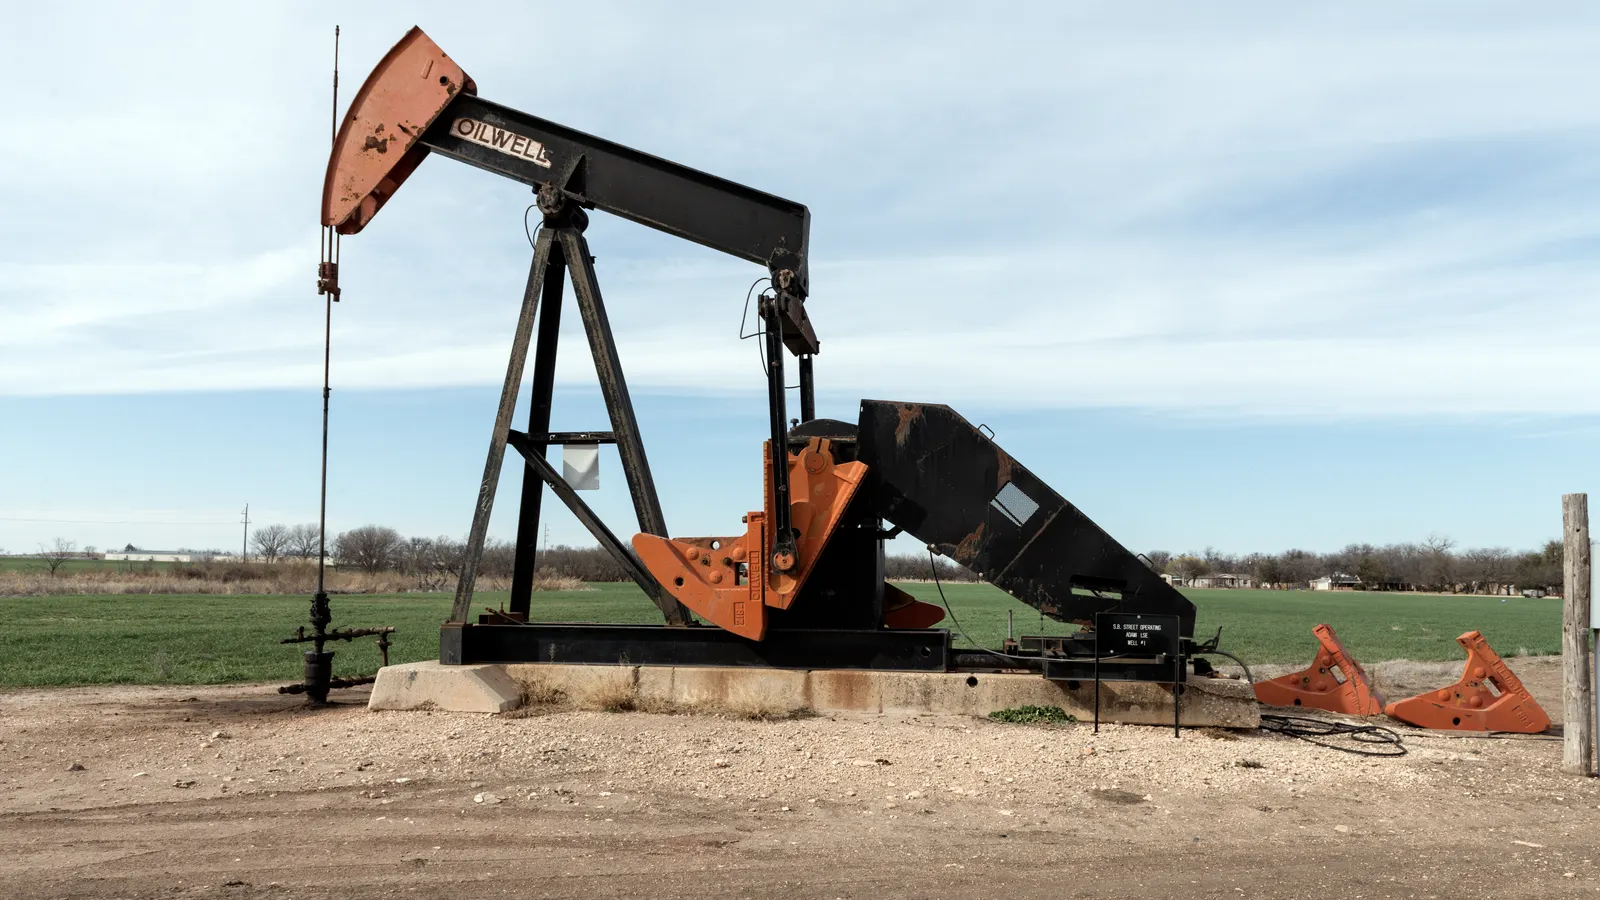
The Permian Basin’s first commercial oil came out of the ground in this county. Santa Rita No. 1 was drilled on Permanent University Fund land near Big Lake, struck oil in 1923, and sent the University of Texas System its first royalty payment, $516.53, that August 24. It was plugged on May 20, 1990, after producing 131,775 barrels in sixty-seven years, per University Lands’ history of the PUF lands.
Hold that against a modern month. In July 2026 the county produced 6,468,955 barrels of crude oil, per the Railroad Commission’s county ranking — roughly forty-nine times Santa Rita’s lifetime output, every thirty days. The useful legacy of 1923 is the ownership map, not the scale. The PUF lands run to 2.1 million acres across nineteen West Texas counties, and Reagan is one of the originals. A meaningful share of this county’s subsurface belongs to the Permanent University Fund, is leased by University Lands under state rules, and cannot be bought from a private owner at any price.
Fee acreage or University Lands: telling which you have
The county was surveyed into blocks and sections, not the metes-and-bounds patchwork of East Texas, so your legal description almost certainly reads as a section, a block and a survey name. University Lands tracts carry their own survey designations, and that is the first thing a title examiner checks. If your description sits inside a University survey, what your family holds is probably surface, not minerals you can sell.
If it is fee land, the chain runs through the Reagan County Clerk in Big Lake, whose records reach back to 1876. One wrinkle trips people up: Reagan sits in Railroad Commission District 7C, run out of San Angelo, not District 08 in Midland, so permits and well records for your acreage sit in a different file than those of the big oil counties immediately north (the Commission publishes the county list). An appraisal notice says somebody thinks you own a producing interest; it is not proof of its size or type.
Mineral acres, fixed royalty, floating royalty
Deeds written here between the 1920s and the 1950s are full of phrases like “one-half of one-eighth” and “one-sixteenth of the usual one-eighth royalty.” Nobody could say reliably what they meant, because at the time almost every lease paid a one-eighth royalty and “1/8” was used loosely as shorthand for the whole mineral estate. In Van Dyke v. Navigator Group, 668 S.W.3d 353 (Tex. 2023), the Texas Supreme Court held that a 1924 reservation of “one-half of one-eighth” conveyed a one-half mineral interest, creating a rebuttable presumption that an old “1/8” means the whole mineral estate rather than a literal fraction. It built on Hysaw v. Dawkins, 483 S.W.3d 1 (Tex. 2016), which refused to mechanically multiply double fractions. The presumption is not absolute: in Clifton v. Johnson, No. 23-0671, decided March 13, 2026, the Court found it rebutted where a 1951 deed stated “1/128” repeatedly as the product of its own double fractions, conveying a fixed 1/128 royalty and nothing more.
The money consequence is permanent. A floating royalty is a share of whatever royalty the current lease carries, so it rises when an operator signs a modern lease above the old one-eighth. A fixed royalty is a share of gross production and never moves. Two neighbors holding near-identical deeds can end up with royalty streams that differ by a multiple. Clifton arose on Reeves County mineral rights tracts across the basin — this is Texas deed law, not a local quirk.
Gassier than its neighbors, and why that shows up on the check
Reagan County sits on the southern margin of the Midland Basin, just north of the Ozona Arch. The column that pays runs from the Wolfcamp A, B and C mudstones up through the Dean sandstone into the Lower Spraberry, the Jo Mill, and the Middle and Upper Spraberry. The county ranked fifth in Texas for crude oil in July 2026, but the character of the stream matters more than the rank: those figures show 46,360,439 Mcf of gas against 6,468,955 barrels of oil — roughly 7,170 cubic feet of gas per barrel, against about 3,420 in Martin County and 4,720 in Upton. On a six-to-one energy basis, gas is about 54 percent of the equivalent barrels produced here, though far less of the revenue.
Three consequences follow. Gas and natural gas liquids, not oil, are where nearly all post-production deductions live, so your lease’s deduction language bites harder here than further north. West Texas gas prices swing far more than oil, so check volatility is normal rather than alarming. And Texas taxes crude oil at 4.6 percent of market value against 7.5 percent for gas, so a gassier county carries a higher blended severance bite. Owners often read the gap between counties as well quality. Some of it is simply gas-oil ratio, which is why weighing Martin County mineral rights against a Reagan tract is not comparing like with like.
On operators, check before you assume. Endeavor Energy Resources, whose Midland Basin position spanned Midland, Martin, Howard, Glasscock, Upton and Reagan counties, became part of Diamondback Energy in September 2024. Pioneer Natural Resources became part of ExxonMobil when that merger closed on May 3, 2024, though records and division orders here still carry the Pioneer name. Apache Corporation still appears on legacy Spraberry units such as the Spraberry Aldwell Unit, where many wells are plugged or shut in. The name on your stub is no guide to who is drilling today.
Turning a decimal into a number
Once the class of interest is settled, the mechanics are ordinary. Your royalty decimal is net mineral acres divided by unit acres, times the lease royalty fraction. Twenty net mineral acres in a 640-acre unit at a one-fifth royalty gives 20 ÷ 640 × 0.20, or 0.00625 — just over half a percent of the unit’s gross revenue, before taxes and deductions. Value comes from what that decimal earns and when. Permian horizontals decline steeply for roughly two years, then flatten into a long tail, so most of a recent well’s present value sits in a short window. Buyers reason in multiples of recent cash flow, but the multiple is no constant you can look up; it falls out of your wells’ decline rate and the buyer’s discount rate. What moves it:
- How much of the section is developed, and how many benches remain untouched beneath it.
- Whether the producing wells are two years old or ten — the remaining curve is a different shape.
- Whether the interest is leased, and at what royalty. Unleased minerals are valued on optionality.
- Whether the lease lets post-production costs be charged against gas and liquids.
Taxes, payment timing and suspended checks
Texas levies no state income tax on royalties, but producing mineral interests are taxable property; Tax Code Section 11.146 exempts an interest whose taxable value is under $500 per taxing unit. On timing, Natural Resources Code Section 91.402 requires a first payment within 120 days after the end of the month of first sale; after that, absent different lease terms, oil is due within 60 days and gas within 90. The section also lets a payor suspend payment during a title dispute. Here, suspended checks are usually a title problem — a University Lands boundary question, or an unresolved double fraction in a deed written before anyone alive had seen a horizontal well.
When to wait, and when selling makes sense
Two situations argue for waiting. Unleased fee minerals in a section with undeveloped Wolfcamp benches beneath existing production are an option, and options are systematically underpriced in unsolicited offers. And a floating royalty under an old lease about to be renegotiated can change in value the day a new lease is signed, handing that increase to a buyer who moved first. Selling tends to make sense when the decimal is too small to justify the paperwork, when the wells are far down the tail with no remaining location, when an estate must be split among heirs who want different things, or when you want certainty instead of a check that moves with gas prices.
Getting a real number on your interest
Bring what you have: the deed or probate papers, any lease, a recent check stub, and the legal description. We will tell you whether the acreage looks like fee minerals or University Lands, what class of interest the instrument creates, and what the wells support — including when the answer is not to sell. Start on our Reagan County mineral rights page, read how we buy and sell Texas mineral rights across the Permian, or contact us and send the documents over.
MINERAL RIGHTS & ROYALTIES
Ready to explore an offer for your mineral rights?
Tell us a little about your interest. Get a free, no-obligation review from Selling My Mineral Rights.